How to Set Membership Dues: Budget, Tiers and Billing
Learn how to set membership dues from your budget, member value and affordability, with a worked USD example, notice steps and an approval checklist.
The board meets in three weeks, the venue invoice came in higher than last year, and someone has already asked the question in the group chat: are we raising dues? Most organizations answer by checking what the club across town charges, or by adding a round percentage to last year's figure. Both are guesses with a vote attached.
Setting membership dues is easier when you work backward. Start with what it costs to run the organization for a year, separate the costs dues are meant to cover, and let the remainder set the target. Then turn that target into a few membership types, pick a billing cycle, and tell members before the invoice does.
That sequence is the short answer to how to set membership dues, and the sections below walk through it with line-by-line arithmetic, hypothetical examples, and a checklist the board can vote on. Have last year's budget and your renewal count in front of you. The exercise takes about an hour.
Calculate Your Dues Target From the Budget
Every dues conversation that goes badly starts in the same place: with last year's number. Begin instead with the annual operating budget and one question. Which costs should dues cover?
For most clubs and associations, the list is shorter than the full budget. Dues usually carry member mailings and the newsletter, a subsidy for member events, meeting space, insurance for membership activities, and the staff or volunteer hours spent on applications, renewals, and member questions. Grants, sponsorships, fundraising, program fees, and facility rentals cover everything else. Keep the two lists separate. A dues rate that pays for the rest of the organization is the rate nobody can explain.
Build in a reserve before dividing anything. An allocation of 25% of core member services is a reasonable starting point for a volunteer-run organization, because it absorbs a mid-year insurance or printing increase without forcing a second vote in the same year.
A worked example for a 310-member club
The figures below are hypothetical and rounded. They're here so you can copy the method, not the amounts.
| Line item | Basis |
|---|---|
| Core member services | Newsletter, events subsidy, meeting space: $36,000 |
| Administration and reserve | 25% of core services: $9,000 |
| Dues target | Core services plus administration: $45,000 |
| Full members | 250 members at $165: $41,250 |
| Reduced-rate members | 60 members at $75: $4,500 |
| Projected dues revenue | Full plus reduced members: $45,750 |
| Cushion | $750 above the dues target, about 1.6% |
Two decisions produced the member rows. The full rate was set first at $165, because full members receive the complete benefit set and their rate sets the expectation for everyone else. The reduced rate of $75 is roughly 45% of the full rate, enough to keep students and retirees in the room without asking full members to carry them entirely.
Then the arithmetic. Two hundred fifty full members at $165 brings in $41,250, and 60 reduced-rate members at $75 adds $4,500. That's $45,750 against a $45,000 target, so the cushion is $750, or about 1.6%.
Practical rule: A cushion under about 5% of the dues target is too thin. One unplanned invoice wipes it out and the board is back to a rate change six months later.
The benefit is easy to see once the numbers sit in a row. Each $5 added to the full rate brings in about $1,250 if those 250 members renew, which is already more than the cushion the example started with.
Write the target on one line
Before anyone opens a competitor's website or last year's renewal report, write the target as a single sentence: dues must raise $45,000 next year from an estimated 250 full and 60 reduced-rate members. Every later decision, about types, proration, or payment plans, becomes a choice about who pays what share of that total.
Treat all of it as an estimate until the actual renewal count is in. The target line gets revised in the first month of the membership year, when real numbers replace the guesses.
Match the Dues Target to Member Value
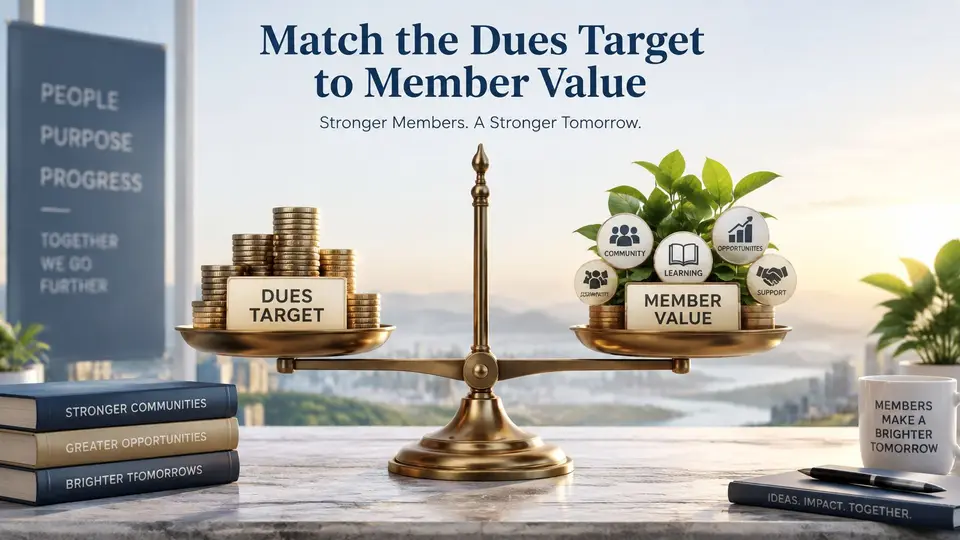
The target says how much the organization needs. It says nothing about what a member receives, and that's the part that decides whether a renewal payment arrives. The balance to strike sits between the number the budget requires and the value a member can point to.
There's a benchmark worth testing against. In a 2018 ASAE membership survey, 82% of respondents said the value of their membership equaled or exceeded the cost of their dues, as reported in the ASAE membership model article. The same article recommends reviewing renewal rates, cancellations, benefit usage, and member feedback after each adjustment, which is the closest thing to a fair test of whether the number was right. If members can't name what the payment buys, even a justified increase reads as arbitrary.
Count renewals, not contacts
Pull last year's renewal records instead of the full contact list. The example club has 310 people in its database and, realistically, fewer than 310 renewals. Budget on the number that renewed last year, adjusted for what you know about this year: 250 full members and 60 reduced-rate members.
Then divide. The $45,000 target spread across 310 members is roughly $145 each, and that average tells you nothing useful, because a student and a working professional can't pay the same amount without one of them leaving.
Set the full rate first, then test a bad year
Set the full rate at $165 and test what happens when renewals fall. A 10% drop leaves 225 full members at $165, or $37,125, plus 60 reduced-rate members at $75, which is $4,500. The total is $41,625, or $3,375 under target.
A dues rate holds when a typical member can answer one question without help: what does this payment pay for?
Close that gap before the board sees the proposal. Another $15 on the full rate recovers exactly $3,375 from 225 members. Trimming the reserve allocation recovers the same sum with no rate change at all, at the cost of a thinner cushion. Either choice is defensible. Discovering the gap in month three is not.
Dues are payment for defined member rights: the newsletter, event access, discounts, facility use, the member portal. A voluntary gift is a separate transaction with separate wording, and keeping them apart stops a donation appeal from reading as a hidden increase.
Price Membership Types and Affordability Tiers
Three to five membership types cover almost every organization. Beyond that, the application form turns into a quiz and the treasurer spends renewal season explaining the difference between categories that sound identical.
Each type earns its place by answering two questions: who does it serve, and which benefits does it include? The table below shows a workable set, with hypothetical annual amounts in USD.
| Membership type | Who it serves | Benefit basis |
|---|---|---|
| Full member | Working professionals and regular participants | All member benefits and event discounts: $165 |
| Reduced rate | Students, retirees, and early-career members | Newsletter and event discounts, limited services: $75 |
| Household | Two adults sharing one address | Full benefits for both adults at one address: $240 |
| Organizational | Businesses or groups that sponsor members | Group listing and organizational access: $450 |
| Hardship waiver | Members with a documented need | Confidential, board-approved, reviewed each year: $0 |
The full member rate of $165 is the reference point. It carries the complete benefit list and most of the revenue, so it's the number to get right first.
For reduced-rate members, $75 buys a narrower package: the newsletter, event discounts, and access to member services, without every add-on. Students, retirees, and early-career members fit here, and the category stays honest only if the benefit list is shorter.
A household type covers two adults at one address for a single combined amount. It's cheaper than two full memberships and cheaper to administer, and a club that adds it adds those people to the same budget worksheet, because household revenue and household costs both move.
Organizational members are businesses or groups that sponsor individual members. They receive a group listing and organizational access, and they usually pay more because they're buying visibility as well as participation.
Handle hardship quietly
A hardship waiver isn't a discount line on the public price list. It's a confidential process with a named contact, a short written request, a decision by two board members, and an annual review. Nobody should have to explain a lost job in a public forum to keep a membership.
Four checks keep the whole schedule defensible. A written definition: one sentence naming who qualifies. A benefit list: what the amount buys, in the member's own words. A named owner: the person who answers questions and approves waivers. A stated reason: why the category exists, phrased so the board can repeat it without notes.
Skip categories that exist mainly to sell a service to nonmembers. A type with a long benefit list and little real participation is hard to defend when someone asks what members get for it.
Write one sentence defining each type before setting any dollar figure. The definition comes first; the price follows it.
Billing Cycles and Partial-Year Joiners
Timing decides how much a member pays, and it's the part new joiners ask about most.
Start with the membership year. January 1 through December 31 matches most budget calendars and keeps reporting simple. A year that starts on each member's join date spreads renewals across twelve months and smooths the workload, at the cost of a harder revenue forecast. Either approach works. Pick one and put the dates in writing.
Then write the proration rule: whether someone joining in month seven pays the full annual rate, a fraction of it, or a monthly amount for the remainder of the year. A published US schedule shows how plainly this can be stated. Association Forum's membership year runs from April 1 through March 31, and members joining in the stated window pay half the annual rate through March 31, with Association Professional listed at $315 annually or $157.50 for the half-year, Chief Staff Executive at $390 or $195, Supporting Member at $485 or $242.50, and Student at $40 or $20, according to Association Forum's half-year dues schedule. The arithmetic stays identical across every level, which is what makes it easy to explain.
| Join point | Share of year remaining | Amount due |
|---|---|---|
| Before the membership year starts | 100% | $165 |
| Six months into the membership year | 50% | $82.50 |
| Nine months into the membership year | 25% | $41.25 |
| Monthly billing, each payment | 12 payments | $13.75 |
State the cutoff date for the reduced rate as an actual date, not as "mid-year." State the renewal date that follows a partial term, so a member who joins in September knows whether the next invoice arrives in January or next September. Then name the person who answers questions about a payment that didn't go through. "The treasurer" is an acceptable answer if it comes with an email address.
Write the rule in three sentences
Three sentences cover it for almost any organization: the membership-year dates, the fraction charged at each point in the year, and the renewal date after a partial term. If a new member can read those sentences and predict their first invoice, the rule is finished. If they have to call, it isn't.
Tell Members About the Change Early
A member who learns the new amount from an invoice treats it as a surprise. A member who hears about it three months earlier treats it as a decision. Announce any change at least 90 days before the new rate takes effect, so the first conversation about the amount isn't also the renewal reminder.
What the notice says, in order
- The reason in one sentence. Tie it to a cost members recognize: venue rent, printing, insurance, or software. Vague references to rising costs invite readers to supply the worst explanation themselves.
- The benefits the dues fund. List what the payment covers, and name the one or two things that changed since last year.
- The new amount, the effective date, and the proration rule. All three in the same place, with the monthly figure shown for anyone who pays monthly.
- The reduced-rate and hardship options. Say they exist and name the person to contact. Members who need them rarely ask a general address.
- A reminder at 30 days with a real channel for questions. Offer a board meeting date or a scheduled member call instead of "reach out anytime."
Keep the donation request out of that notice. When a voluntary gift appears beside a required increase, members read the whole message as a bill that grew. Send the appeal separately, weeks apart.
Wording that works: "Starting January 1, annual dues will be $165, up from $150, to cover rising printing and venue costs."
That sentence is a hypothetical example, and it shows the required ingredients: the date, the new figure, the old figure, and a reason tied to something a member can picture.
Draft the notice before the board meets, not after, so the board reviews the exact wording members will read rather than a summary of it. If the wording can't be made clear and short, the pricing decision isn't finished yet.
Approval Checklist Before You Publish New Dues
The board's job is confirmation, not discovery. Send this list with the proposal so every line has an answer before the vote.
- The math matches the budget. The dues target on the worksheet is the target in the approved operating budget, and the treasurer has tested it against a realistic renewal count rather than the full contact list.
- Every membership type has a definition, a benefit list, and an owner. A type without an owner has nobody to answer questions about it in March.
- The rates and rules sit in one document. Reduced-rate eligibility, hardship handling, billing cycle, proration fraction, and cutoff date belong on the same page.
- The member notice is drafted and dated. At least 90 days before the effective date, with the reminder scheduled for 30 days out.
- The records reflect the new amounts before the first invoice. Renewal records and any membership software settings get updated before renewal season starts, not during it.
- The decision is recorded. Amount, reason, effective date, and the vote go into the minutes, along with a review date for next year.
This checklist doesn't set approval requirements. Follow your bylaws and board policies for who votes on a dues change, what notice the membership receives, and how the decision gets documented.
Load the Approved Dues Before Renewal
The last step is mechanical, and it's where a sound decision turns into a billing error if nobody owns it.
- Enter each membership type with its annual amount. The $165 and $75 figures from the example are placeholders until the approved numbers replace them.
- Set the calendar rules. Membership-year start, proration fractions, cutoff date, and the day the first renewal invoice goes out.
- Test one member record. Confirm the amount, due date, and payment status match the schedule before touching the rest.
- Schedule the messages. Notice at 90 days, reminder at 30, and any donation appeal in its own separate send.
- File the decision. Amount, reason, effective date, and the name of the person who answers billing questions, stored alongside the minutes.
campai membership management software connects member records, dues and billing, online payments, events, and communication, so a coordinator can track due dates and send reminders from the organization's own settings. Bring the current member list, the dues schedule, and the approved minutes to a demo and work through the setup on your own numbers.
Set the schedule up once and renewal season becomes a review instead of a rebuild. Book a demo with the member list and the approved dues schedule in hand.